
 Contact
 Cum să cumpăr

Livrare
Consilier de cumpărături
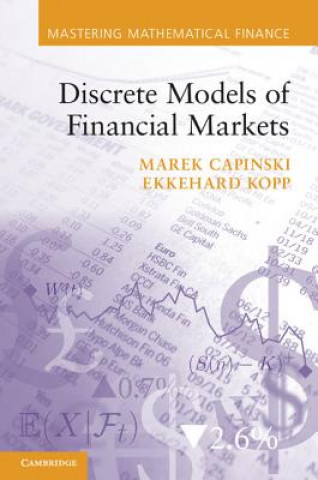
Discrete Models of Financial Markets
 engleză
 172 b
Până la 30 de zile pentru returnare
Clienții au cumpărat de asemenea




 /
 Carte broșată
 212.87
lei





 /
Carte broșată
96.28
lei


 /
Carte broșată
178.41
lei


This book explains in simple settings the fundamental ideas of financial market modelling and derivative pricing, using the no-arbitrage principle. Relatively elementary mathematics leads to powerful notions and techniques – such as viability, completeness, self-financing and replicating strategies, arbitrage and equivalent martingale measures – which are directly applicable in practice. The general methods are applied in detail to pricing and hedging European and American options within the Cox–Ross–Rubinstein (CRR) binomial tree model. A simple approach to discrete interest rate models is included, which, though elementary, has some novel features. All proofs are written in a user-friendly manner, with each step carefully explained and following a natural flow of thought. In this way the student learns how to tackle new problems.


Informații despre carte
engleză

Dăruiește această carte chiar astăzi
Este foarte ușor
1 Adaugă cartea în coș și selectează Livrează ca un cadou 2 Îți vom trimite un voucher în schimb 3 Cartea va ajunge direct la adresa destinataruluiAr putea de asemenea, să te intereseze

 /
Carte broșată
53.29
lei





 /
Carte broșată
64.11
lei






 /
Carte broșată
689.95
lei
Bună ziua! Sunt Libroamiko, consilierul dumneavoastră de cărți.
Cu ce vă pot ajuta?